January 2025
Fed chief Powell spoils New Year’s Eve party.
This issue provides an in-depth analysis of the global financial landscape, with a review of a turbulent end to 2024 and an outlook for the new investment year.
Published 8 January 2025By Investment TeamReading time 2 minAlso in German Marktkompass
Our view on the markets and investment strategy in the January 2025 Market Compass.
Highlights Include
Fed Disappoints Investors at Year‑End
The Federal Reserve concluded 2024 with a third consecutive rate cut, reducing the target range to 4.25%–4.50%. However, Fed Chairman Powell signaled a more gradual pace for rate cuts in 2025, revising the outlook to two cuts instead of the previously expected four. This led to a -2.5% decline for the S&P 500 in December, while European indices like the DAX (+1.4%) and EuroStoxx 50 (+1.9%) outperformed.
Rising Yields Weigh on Fixed Income Markets
Despite ongoing rate cuts, US 10-year Treasury yields continued to rise, nearing the April 2024 peak of 4.73%. This upward pressure, partly driven by concerns over President-elect Trump’s expansionary fiscal policies, poses significant risks for both equity and bond markets.
Tech Dominates Market Performance
The S&P 500 posted a strong 23.3% return for 2024, with over half of the index’s gains attributed to just seven tech giants—the “Magnificent Seven.” Nvidia led the pack with a 172% annual return, underscoring the importance of disciplined stock selection in concentrated markets.
Market Outlook for 2025
The upcoming earnings season is expected to reveal an 11.9% year-over-year growth in Q4 earnings for the S&P 500, led by Silicon Valley firms. We maintain a constructive view on technology and communication services, with structural trends like AI continuing to drive growth. However, heightened political risks around the new US administration prompt a neutral equity allocation with a preference for US and Emerging Markets like India and Vietnam.
Opportunities in Fixed Income and Gold
The recent spike in yields offers attractive risk-adjusted returns in US fixed income markets, while gold remains an effective hedge against inflation and geopolitical uncertainties. Falling real interest rates, a weaker US dollar, and strong central bank demand further support the outlook for gold.
Ready to dive in? Download the full PDF of our January 2025 Market Compass for a detailed analysis and forward-looking guidance on navigating today’s financial markets.
Do not hesitate to contact us with any questions about the topics discussed. We are happy to assist you with our expertise.
01
The full edition
01 / 03
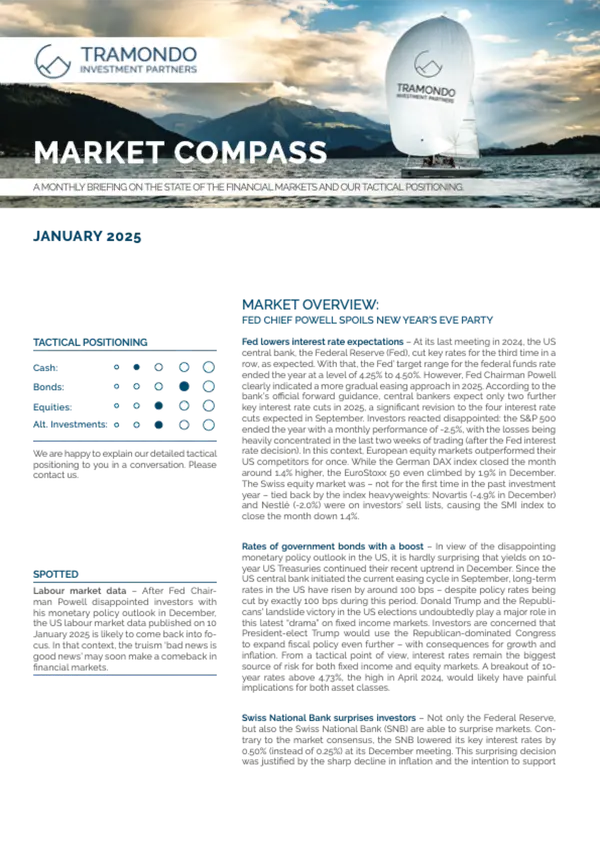
Read the full Market Compass. January 2025.
Our in-depth outlook with scenarios, risks and positioning, as published: the edition as a PDF, in English and German.
- Market Compass, January 2025PDF · English
- Marktkompass, Januar 2025PDF · Deutsch
02
By e‑mail
02 / 03
Get the Market Compass by e‑mail
Every month, in English or German.
03
Previous editions
03 / 03
Previous editions
Market Compass · 8 Nov 2024
Market Compass November 24 - Investors under the spell of the US elections
We are pleased to count you among our Market Compass readers. The monthly publication provides interesting insights and suggestions regarding the current market environment.
Market Compass · 4 Oct 2024
Market Compass October 24 - China and Powell send markets higher
We are pleased to count you among our Market Compass readers. The monthly publication provides interesting insights and suggestions regarding the current market environment.
Market Compass · 6 Sep 2024
Market Compass September 24 - Not for the faint of heart...
We are pleased to count you among our Market Compass readers. The monthly publication provides interesting insights and suggestions regarding the current market environment.