June 2025
Trump retreats.markets advance.
This issue highlights a softer stance from the US administration on trade—at least temporarily—resilient performance from the “Magnificent Seven,” and key implications for portfolio positioning.
Published 11 June 2025By Investment TeamReading time 1 minAlso in German Marktkompass
Our view on the markets and investment strategy in the June 2025 Market Compass.
Highlights Include
Trump’s softer tone – but for how long?
US President Trump softened his tone in May, offering temporary tariff relief with China and the EU—yet by month-end, trade rhetoric picked up again, leaving investors cautious.
Tech shines amid volatility
Large-cap Silicon Valley names delivered a strong performance in May, with Meta Platforms (+17.9%) and Microsoft (+16.7%) leading the charge. Tesla (+22.8%) rebounded after Elon Musk shifted focus back to operations. Apple, however, lagged the group, ending May down 5.5%—a reminder that selectivity matters.
China’s auto market in focus
A slowdown in Chinese growth is weighing on EV demand, with BYD cutting prices by up to 35%. The stock fell 15.6% in late May, underscoring the risks tied to China’s economic cycle.
Share buybacks support equities
US companies with regular buyback programs have historically outperformed the broader market. We explain why and how this trend could continue to support US equity markets, despite near-term uncertainty.
Positioning for volatility
We maintain a slightly underweight allocation in equities, favoring quality and balanced sector exposure. We remain neutral on gold, seeing potential to add exposure on pullbacks, and continue to emphasize high-quality bonds as a hedge.
Ready to dive in? Download the full PDF of our June 2025 Market Compass
for a detailed analysis and forward-looking guidance on navigating today’s financial markets.
Do not hesitate to contact us with any questions about the topics discussed. We are happy to assist you with our expertise.
01
The full edition
01 / 03
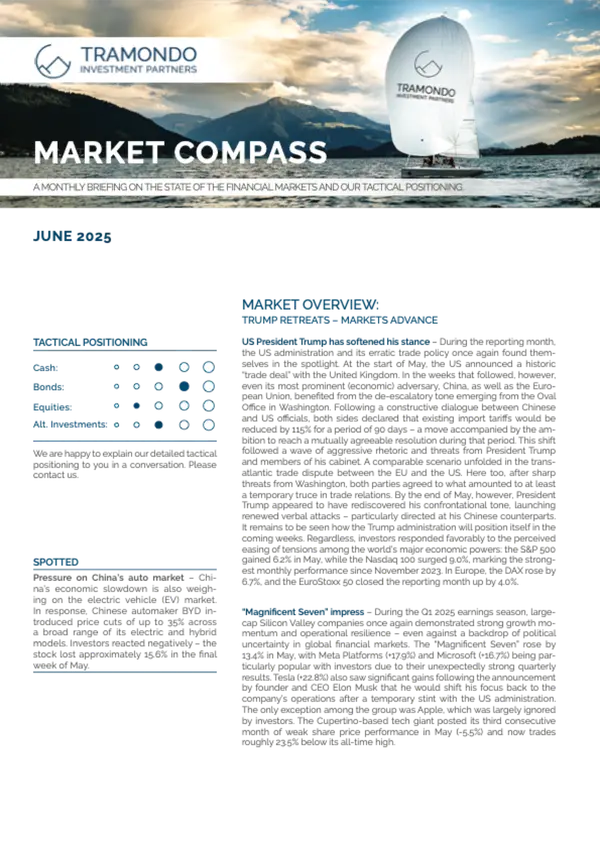
Read the full Market Compass. June 2025.
Our in-depth outlook with scenarios, risks and positioning, as published: the edition as a PDF, in English and German.
- Market Compass, June 2025PDF · English
- Marktkompass, Juni 2025PDF · Deutsch
02
By e‑mail
02 / 03
Get the Market Compass by e‑mail
Every month, in English or German.
03
Previous editions
03 / 03
Previous editions
Market Compass · 6 May 2025
Market Compass May 25 - Trump faces pushback from investors
Our view on the markets and investment strategy in the May 2025 Market Compass.
Market Compass · 7 Apr 2025
CIO Market Flash - Tramondo's take on «Liberation Day»
With US tariffs escalating far beyond expectations, markets are reacting fast—and so are we. In this special CIO Update, find out how Tramondo is adjusting equity exposure, reassessing global risks …
Market Compass · 6 Mar 2025
Market Compass March 25 - Europe in the fast lane
Our view on the markets and investment strategy in the March 2025 Market Compass.