April 2026
When geopolitics meets fundamental resilience.
Iran conflict shakes financial markets - The sharp rise in oil prices - Brent crude surged from $72.5 to $118.4 in March, a historic gain of +63.3% - fueled global concerns about renewed inflationary pressure and a more restrictive monetary policy.
Published 8 April 2026By Investment TeamReading time 3 minAlso in German Marktkompass
Our view on the markets and investment strategy in the April 2026 Market Compass.
March was dominated by the geopolitical escalation in the Middle East, with the Iran conflict leaving its mark on financial markets far beyond the oil sector. What initially appeared to be a classic oil and inflation shock quickly developed into a broad-based stress event for global capital markets. Despite the tense environment, fundamentals continued to provide an important support, and the macroeconomic backdrop remained remarkably resilient - especially in the United States.
Iran conflict shakes financial markets
The sharp rise in oil prices - Brent crude surged from $72.5 to $118.4 in March, a historic gain of +63.3% - fueled global concerns about renewed inflationary pressure and a more restrictive monetary policy. This combination proved particularly toxic for markets: not only equities and other risk assets came under pressure, but also supposedly safe havens. Rising yields weighed on US sovereign bonds, and even gold was only able to fulfil its hedging function to a limited extent. For investors, this created an exceptionally challenging environment in which diversification across asset classes temporarily worked far less effectively than usual.
Central banks remain in wait‑and‑see mode
On 18 March, the US Federal Reserve left its policy rate unchanged, emphasizing that economic activity was still expanding at a solid pace while pointing to uncertain implications of Middle East developments. The ECB also kept rates unchanged on 19 March. The oil price shock prompted a meaningful reassessment of the monetary policy outlook: in the US, investors were no longer pricing in any additional rate cuts by year-end, while in the Eurozone, markets were even discounting around three rate hikes by the end of 2026.
Robust economic data provide a counterweight
The ISM Manufacturing Index rose to 52.7, signaling expansion in the industrial sector for a third consecutive month. However, the ISM price component jumped to 78.3, reaching its highest level since June 2022. The data were strong enough to keep recession fears at bay, but also robust enough to leave central banks with little room for swift rate cuts.
Alphabet and Meta found liable
A US court concluded that the two social media companies failed to adequately warn users about the risks of addiction. The plaintiff was awarded $3 million in damages. The ruling could set an important precedent, as hundreds of similar lawsuits are pending and may challenge the business model of the tech giants.
April's two faces - a seasonal pattern worth watching
Historically, April has been an excellent month for equity investors. The S&P 500 has delivered an average return of around 1.5%, more than double its long-term monthly average of 0.7% since 1950. An interesting pattern emerges within the month: the second half has historically been significantly stronger than the first, driven by the US tax filing deadline of 15 April. Once this outflow of liquidity subsides, buying power tends to return to the market. At Tramondo, we monitor such seasonality patterns closely but never consider them in isolation.
Q1 2026 earnings season ahead
From mid-April, fundamentals are likely to move back into focus. Analysts expect earnings growth of 13.2% for the S&P 500. Investors will pay particular attention to company guidance and management commentary for clues on any impact of the Middle East conflict on business performance.
What is next and how we are positioned
The oil price remains the key risk variable for equity markets. Europe appears particularly vulnerable given its greater dependence on energy imports. In this environment, high-quality US companies with strong balance sheets, stable margins, and significant pricing power are likely to outperform. Our tactical stance: Cash 2/5, Fixed Income 3/5, Equities 3/5 with a selective quality focus, and Alternative Investments upgraded to 4/5 - reflecting our conviction in gold, where recent weakness has clearly improved the risk-return profile.
Download the full Market Compass April 2026 PDF
Access our in-depth outlook, tactical positioning details, and our complete thesis on navigating geopolitical risk alongside fundamental resilience. Download the PDF now to explore our scenarios, risks, and portfolio positioning in detail.
Ready to dive in?
Download the full PDF of our April 2026 Market Compass for a detailed analysis and forward-looking guidance on navigating today's financial markets.
Do not hesitate to contact us with any questions about the topics discussed. We are happy to assist you with our expertise.
01
The full edition
01 / 03
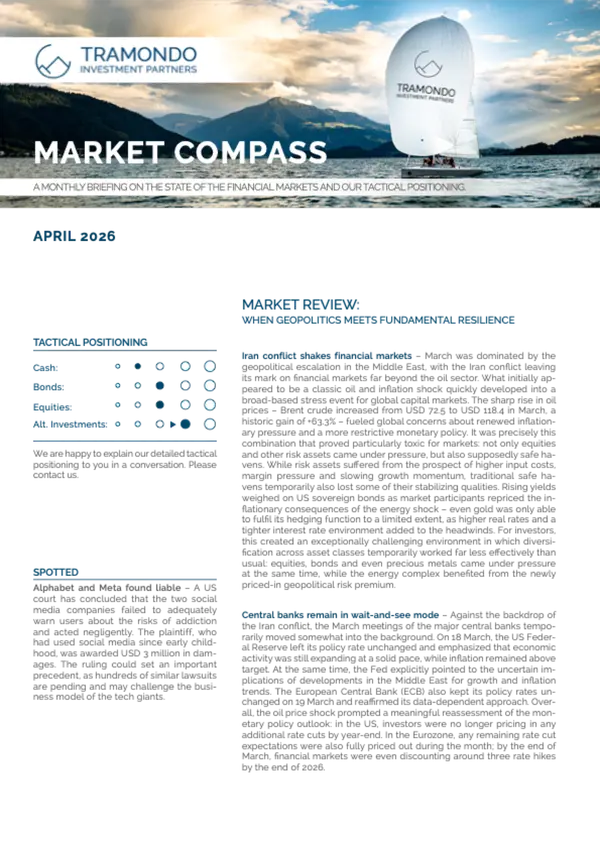
Read the full Market Compass. April 2026.
Our in-depth outlook with scenarios, risks and positioning, as published: the edition as a PDF, in English and German.
- Market Compass, April 2026PDF · English
- Marktkompass, April 2026PDF · Deutsch
02
By e‑mail
02 / 03
Get the Market Compass by e‑mail
Every month, in English or German.
03
Previous editions
03 / 03
Previous editions
Market Compass · 5 Mar 2026
Market Compass March 26 - AI skepticism and tariff reform
Our view on the markets and investment strategy in the March 2026 Market Compass.
Market Compass · 5 Feb 2026
Market Compass February 26 - Powell stands firm, commodity markets falter
Our view on the markets and investment strategy in the February 2026 Market Compass.
Market Compass · 8 Jan 2026
Market Compass January 26 - Equity markets enter the final sprint
Our view on the markets and investment strategy in the January 2026 Market Compass.