July 2026
De‑escalation in the Middle East, but monetary headwinds persist.
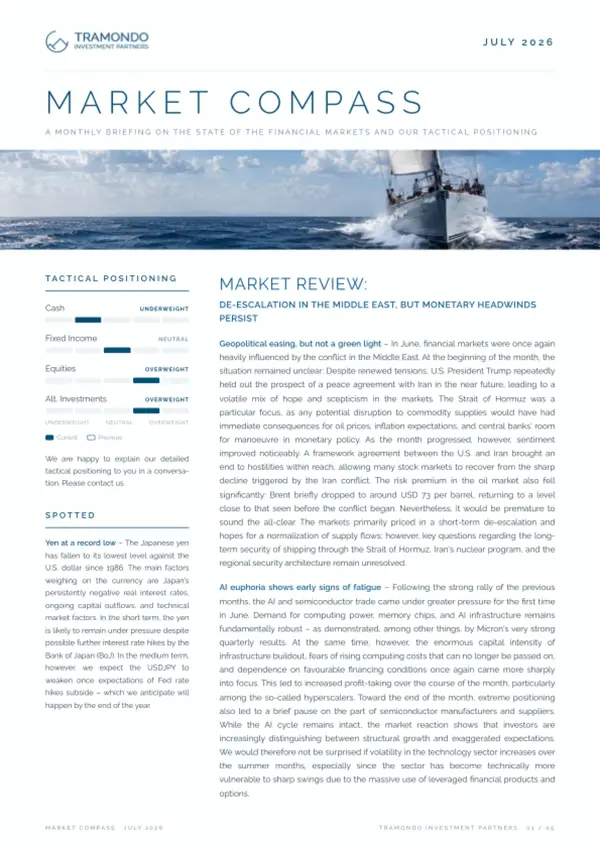
A strong first half of the year on global stock markets will most likely be followed by a positive second half. Earnings growth remains robust, earnings revisions are positive across several sectors, and the earnings cycle is gradually broadening beyond the major AI beneficiaries.
Published 6 July 2026By Investment TeamReading time 3 minAlso in German Marktkompass
Our view on the markets and investment strategy in the July 2026 Market Compass.
Geopolitical tensions have eased but not disappeared, while central banks continue to navigate a complex inflation landscape that demands investor vigilance and selectivity.
De‑escalation in the Middle East, but no all‑clear
A framework agreement between the U.S. and Iran brought an end to hostilities within reach, allowing stock markets to recover from the sharp decline triggered by the conflict. Brent crude briefly dropped to around USD 73 per barrel, returning to pre-conflict levels. However, key questions regarding the long-term security of the Strait of Hormuz, Iran's nuclear program, and the regional security architecture remain unresolved. The risk of another oil price shock has not disappeared - it has merely receded into the background.
AI euphoria shows early signs of fatigue
Following a strong rally in previous months, the AI and semiconductor trade came under greater pressure for the first time in June. Micron's very strong quarterly results confirmed that demand for computing power and AI infrastructure remains fundamentally robust. At the same time, the enormous capital intensity of infrastructure buildout, fears of rising costs, and extreme positioning led to increased profit-taking among hyperscalers and semiconductor suppliers. We would not be surprised if volatility in the technology sector increases over the summer months.
Hawkish hold from the new Fed Chair
The Fed left its policy rate unchanged at 3.50% to 3.75%, but markets clearly interpreted the first meeting under new Fed Chair Kevin Warsh as hawkish. His strong emphasis on the 2% inflation target prompted investors to revise interest rate expectations upward, driving a noticeable rise in short-term U.S. yields. Speculation about rate cuts remains limited for the time being. The ECB raised its deposit rate by 25 bps to 2.25%, responding to energy-driven inflation risks - a move that in our view increases the risk of a monetary policy misstep weighing on growth in 2027.
Yen at a record low
The Japanese yen has fallen to its lowest level against the U.S. dollar since 1986, weighed down by persistently negative real interest rates, ongoing capital outflows, and technical market factors. In the medium term, however, we expect USDJPY to weaken once expectations of Fed rate hikes subside - which we anticipate will happen by year-end.
History favours the bulls after a strong first half
When the MSCI World Index has closed the first six months in positive territory, it has historically posted further gains in the second half in 75% of cases. If the early rally clears the 5% hurdle, that probability climbs to nearly 90%. With global stocks up about 9% after the first half of this year, the historical pattern strongly favours staying invested. A strong start is not a warning signal to exit, but rather a statistical invitation to stay the course.
How we are positioned
We remain overweight in equities, with a focus on the U.S. market for its combination of earnings visibility, balance sheet quality, and access to AI value chains. Any temporary weakness would represent healthy consolidation rather than a trend reversal. Our tactical stance: Cash 2/5, Fixed Income 3/5 with a preference for quality issuers and disciplined duration, Equities 4/5 with U.S. preference, and Alternative Investments 4/5 with gold as a strategic portfolio stabilizer. S&P 500 earnings growth of 23.1% is expected for Q2 2026, once again driven largely by major tech stocks.
Download the full Market Compass July 2026 PDF
Access our in-depth outlook, sector and regional playbooks, fixed income implementation ideas, and our detailed thesis. Download the PDF now to explore our scenarios, risks, and portfolio positioning in detail.
Ready to dive in?
Download the full PDF of our July 2026 Market Compass for a detailed analysis and forward-looking guidance on navigating today's financial markets.
Do not hesitate to contact us with any questions about the topics discussed. We are happy to assist you with our expertise.
01
The full edition
01 / 03
Read the full Market Compass. July 2026.
Our in-depth outlook with scenarios, risks and positioning, as published: the edition as a PDF, in English and German.
- Market Compass, July 2026PDF · English
- Marktkompass, Juli 2026PDF · Deutsch
02
By e‑mail
02 / 03
Get the Market Compass by e‑mail
Every month, in English or German.
03
Previous editions
03 / 03
Previous editions
Market Compass · 4 Jun 2026
Market Compass June 26 - AI boom overshadows weak market breadth and geopolitical risks
Our view on the markets and investment strategy in the June 2026 Market Compass.
Market Compass · 6 May 2026
Market Compass May 26 - Resilient corporate earnings in an uncertain environment
Our view on the markets and investment strategy in the May 2026 Market Compass.
Market Compass · 8 Apr 2026
Market Compass April 26 - When geopolitics meets fundamental resilience
Our view on the markets and investment strategy in the April 2026 Market Compass. March was dominated by the geopolitical escalation in the Middle East, with the Iran conflict leaving its mark on …