June 2026
AI boom overshadows weak market breadth and geopolitical risks.
Global equity markets delivered strong gains in May, but beneath the surface, market breadth remained remarkably narrow. The semiconductor sector continued to surge on insatiable demand for AI computing power, while geopolitical tensions in the Middle East showed few signs of lasting deescalation.
Published 4 June 2026By Investment TeamReading time 3 minAlso in German Marktkompass
Our view on the markets and investment strategy in the June 2026 Market Compass.
Against this backdrop, we are upgrading equities to Overweight and continue to favour US equities alongside selected global companies positioned to benefit from the ongoing AI, semiconductor and infrastructure investment cycle.
No agreement yet in the Iran conflict
The Iran conflict remained a key geopolitical risk factor in May. Negotiations between the United States and Iran stalled once again, with President Trump calling for further amendments regarding the Strait of Hormuz and highly enriched uranium. The military situation deteriorated further, and Iran's threat to fully block the Strait of Hormuz continues to keep the risk of a renewed oil price shock elevated. For financial markets, the conflict remains a structural risk to inflation, energy supply and the flexibility of monetary policy.
Semiconductor stocks continue to surge
The Philadelphia Semiconductor Index delivered an impressive gain of 22.1% in May, marking its strongest start to a year since the 1990s with a year-to-date return of 81.5%. Micron surged 88.6% during the month and 240.4% year to date, becoming the first memory chip manufacturer to surpass a market capitalisation of USD 1 trillion. Equipment suppliers also benefited strongly: Lam Research (+23.4%), Applied Materials (+14.1%) and ASML (+13.3%). NVIDIA reported revenue growth of 85% year on year but gained a comparatively modest 5.8% as much of the positive news had already been priced in.
Market breadth on Wall Street remains weak
The S&P 500 gained 5.2% and the Nasdaq 100 advanced 10.5% in May, but only three of eleven S&P 500 sectors posted positive returns: Information Technology (+15.9%), Consumer Discretionary (+2.6%) and Healthcare (+2.3%). This narrow leadership more than offset weakness across sectors more closely linked to the real economy. In Europe, the Euro Stoxx 50 gained 2.9%, the STOXX Europe 600 rose 2.4% and the Swiss Performance Index advanced 3.3%.
Nine consecutive weeks of gains - a rare feat
The S&P 500 ended May with nine consecutive weeks of gains, recording 11 new all-time closing highs and reaching a record above 7,580 points. This achievement has occurred only 13 times since the 1930s. Historical data shows that rather than signalling an imminent reversal, such streaks have typically been followed by continued momentum, with average four-week returns of 1.2% and three-month returns of 4.4% - both well above long-term averages. History suggests that attempting to time the exact peak of such rare winning streaks is usually a losing battle.
ECB rate decision in focus
On 11 June, the European Central Bank holds its next policy meeting. Markets are widely expecting a 25 basis point increase in the key policy rate, driven by rising inflation risks following the effective closure of the Strait of Hormuz. In the United States, the Federal Reserve is likely to remain cautious for longer as the labour market appears resilient and inflation data is expected to stay elevated in the near term.
How we are positioned
We are upgrading equities from Neutral to Overweight, formally recognising the positioning that has already emerged over recent months. Our tactical stance: Cash 2/5, Fixed Income 3/5, Equities 4/5 (upgraded to Overweight) and Alternative Investments 4/5. Gold remains Strongly Overweight, with the price approaching its 200-day moving average near USD 4,400 per ounce following an almost 20% decline from the late January peak. We view recent weakness as a consolidation within an intact medium-term uptrend.
Download the full Market Compass June 2026 PDF
Access our in-depth outlook, sector and regional playbooks, fixed income positioning and our detailed investment thesis. Download the PDF now to explore our scenarios, risks and portfolio positioning in detail.
Ready to dive in?
Download the full PDF of our June 2026 Market Compass for a detailed analysis and forward-looking guidance on navigating today's financial markets.
Do not hesitate to contact us with any questions about the topics discussed. We are happy to assist you with our expertise.
01
The full edition
01 / 03
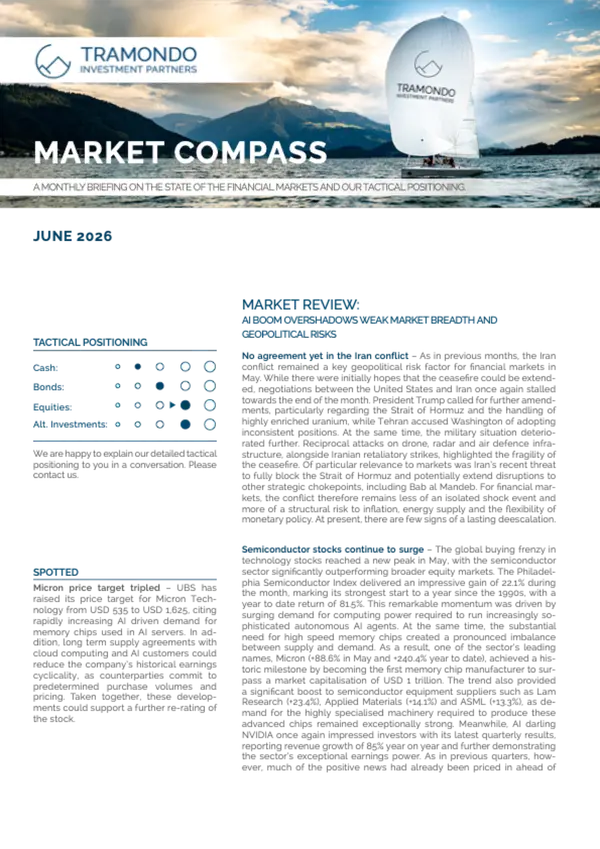
Read the full Market Compass. June 2026.
Our in-depth outlook with scenarios, risks and positioning, as published: the edition as a PDF, in English and German.
- Market Compass, June 2026PDF · English
- Marktkompass, Juni 2026PDF · Deutsch
02
By e‑mail
02 / 03
Get the Market Compass by e‑mail
Every month, in English or German.
03
Previous editions
03 / 03
Previous editions
Market Compass · 6 May 2026
Market Compass May 26 - Resilient corporate earnings in an uncertain environment
Our view on the markets and investment strategy in the May 2026 Market Compass.
Market Compass · 8 Apr 2026
Market Compass April 26 - When geopolitics meets fundamental resilience
Our view on the markets and investment strategy in the April 2026 Market Compass. March was dominated by the geopolitical escalation in the Middle East, with the Iran conflict leaving its mark on …
Market Compass · 5 Mar 2026
Market Compass March 26 - AI skepticism and tariff reform
Our view on the markets and investment strategy in the March 2026 Market Compass.