November 2026
AI investments under scrutiny and bonds on the rise.
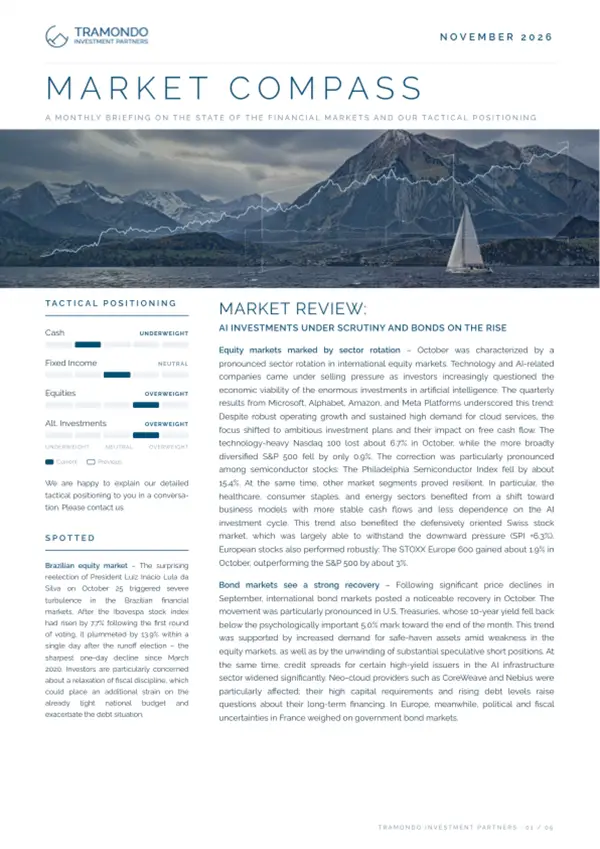
October brought a sharp sector rotation to global equity markets as investors began to question the economic viability of the enormous capital expenditure flowing into artificial intelligence. At the same time, bond markets staged a noticeable recovery after September's sell-off.
Published 6 November 2026By Investment TeamReading time 3 minAlso in German Marktkompass
Explore the latest trends and strategic insights in the November 2026 edition of the "Market Compass."
We remain constructive on equities and maintain our tactical overweight, while viewing the improved risk-reward profile in fixed income as an opportunity to earn attractive running income alongside capital appreciation potential.
AI investments under scrutiny
Technology and AI-related companies came under selling pressure in October. Despite robust operating growth and sustained demand for cloud services, quarterly results from Microsoft, Alphabet, Amazon, and Meta Platforms shifted investor focus to ambitious investment plans and their impact on free cash flow. The Nasdaq 100 lost about 6.7%, while the broader S&P 500 fell just 0.9%. Semiconductors bore the brunt, with the Philadelphia Semiconductor Index down about 15.4%.
Defensive markets prove resilient
Healthcare, consumer staples, and energy benefited from a shift toward business models with stable cash flows and less dependence on the AI investment cycle. The defensively oriented Swiss market withstood the downward pressure, with the SPI gaining 6.3%. European equities were also robust: the STOXX Europe 600 rose about 1.9%, outperforming the S&P 500 by roughly 3%.
Bonds rally as yields retreat
International bond markets recovered noticeably following September's price declines. The move was most pronounced in US Treasuries, where the 10-year yield fell back below the psychologically important 5.0% mark. Safe-haven demand and the unwinding of substantial speculative short positions supported the rally. At the same time, credit spreads widened sharply for high-yield issuers in AI infrastructure, with neo-cloud providers such as CoreWeave and Nebius under particular scrutiny given their capital requirements and rising debt levels.
Central banks take a break from rate hikes
The Federal Reserve left its benchmark rate unchanged at 3.75% to 4.00%, with Chairman Warsh pointing to a robust economy and persistent price pressures, and two FOMC members already advocating a further 0.25% increase. The ECB held its deposit rate at 2.50% with inflation at 3.8% and growth prospects weakening, while the Bank of Japan kept its key rate at 1.25%. The pause does not change the restrictive stance: further hikes are by no means ruled out.
Spotted: turbulence in Brazil
The surprising reelection of President Luiz Inacio Lula da Silva on 25 October triggered severe turbulence. After rising 7.7% following the first round, the Ibovespa plummeted 13.9% in a single day after the runoff, the sharpest one-day decline since March 2020. Investors fear a relaxation of fiscal discipline and a worsening debt situation.
Soon in focus: Anthropic's IPO and the lesson of newly listed stocks
The developer of the AI model Claude is poised for one of the largest listings in history, potentially valuing the company at USD 1.5 to 2 trillion. The IPOX-100 Index, which tracks newly listed US companies over their first 1,000 trading days, has outperformed the S&P 500 over extended periods, yet returns are typically dominated by a handful of exceptional winners such as Nvidia, which listed in 1999 alongside 475 other companies. Limited track records, ambitious valuations, and expiring lock-up periods make us cautious. What matters is not investing as early as possible, but investing at the right price in a company with compelling fundamentals.
What's next and how we are positioned
The US midterm elections on 3 November reshaped the balance of power in Washington, yet earnings, growth, and monetary policy remain the far more important drivers of medium-term equity returns. We expect a "Hiking Cycle Light" with one further 25 basis point Fed move in December and possibly one more in early 2027. Our tactical stance: Cash 2/5, Fixed Income 3/5 with neutral duration and a focus on high quality, Equities 4/5 favoring the United States and the broader AI value chain, Alternative Investments 4/5 with gold as our preferred diversifier.
Ready to dive in?
Download the full PDF of our November 2026 Market Compass for a detailed analysis and forward-looking guidance on navigating today's financial markets.
Do not hesitate to contact us with any questions about the topics discussed. We are happy to assist you with our expertise.
01
The full edition
01 / 03
Read the full Market Compass. November 2026.
Our in-depth outlook with scenarios, risks and positioning, as published: the edition as a PDF, in English and German.
- Market Compass, November 2026PDF · English
- Marktkompass, November 2026PDF · Deutsch
02
By e‑mail
02 / 03
Get the Market Compass by e‑mail
Every month, in English or German.
03
Previous editions
03 / 03
Previous editions
Market Compass · 5 Oct 2026
Market Compass October 26 - Rising yields weigh on markets – AI provides support
Our view on the markets and investment strategy in the October 2026 Market Compass.
Market Compass · 3 Sep 2026
Market Compass September 26 - Tech back on track, Fed keeps its foot on the brake
Our view on the markets and investment strategy in the September 2026 Market Compass.
Market Compass · 5 Aug 2026
Market Compass August 26 - AI euphoria gives way to increasing selectivity
Our view on the markets and investment strategy in the August 2026 Market Compass.